Elon Musk’s dream merger is a nightmare for SpaceX shareholders
 Dante Ulanday - News Writer and Moderator
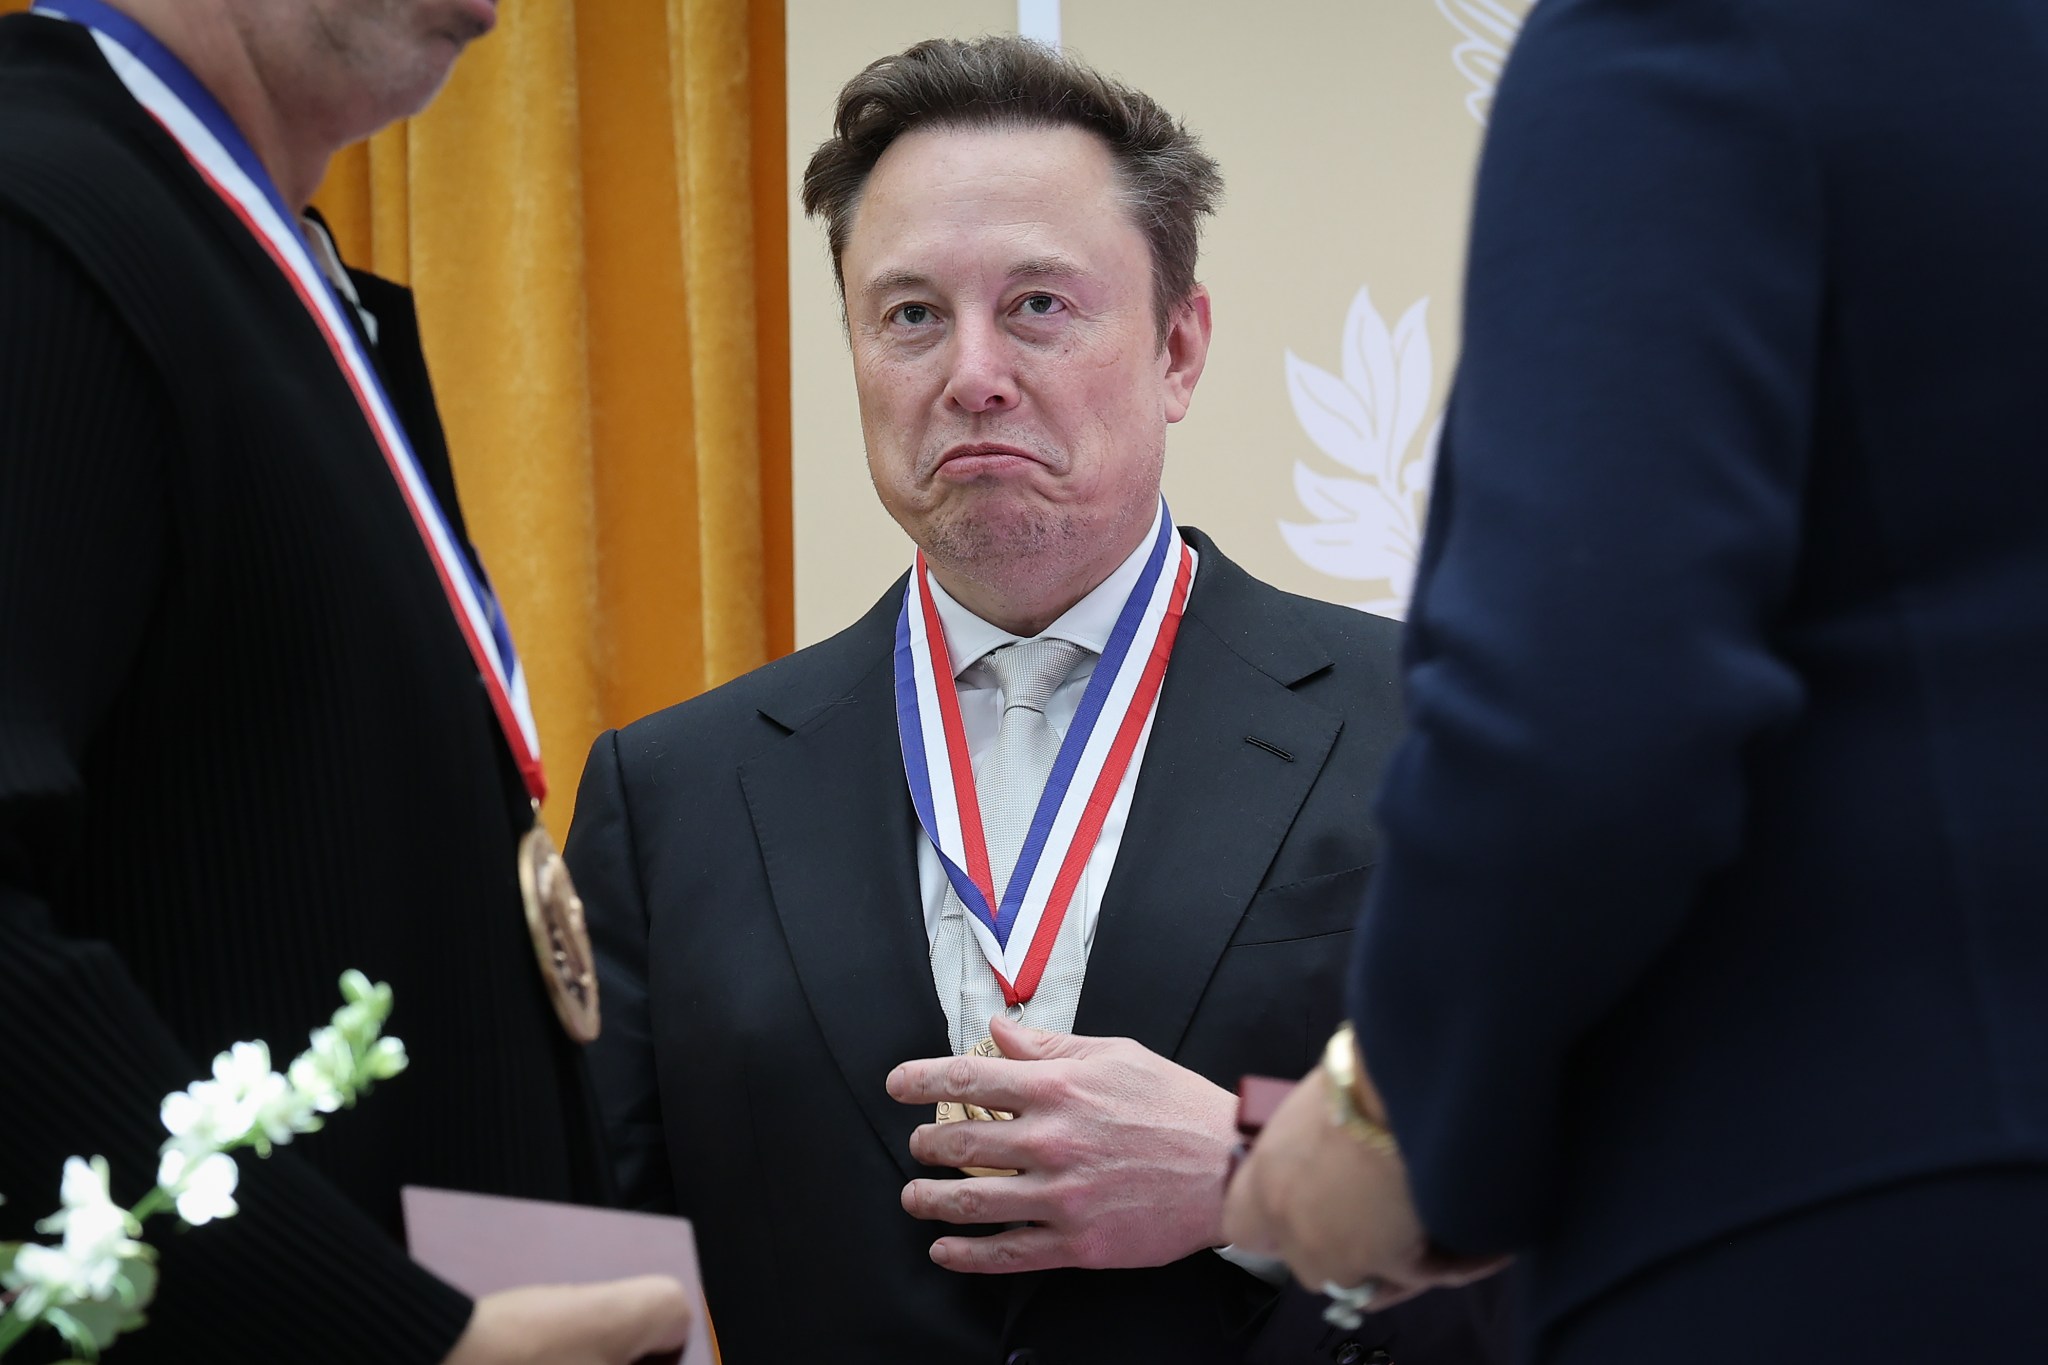
The blowout news from SpaceX’s Q3 earnings wasn’t the rocket and AI giant’s outstanding performance that far exceeded even the analysts’ elevated expectations, but Elon Musk’s revelation that SpaceX and Tesla are weighing a merger. On the call, held the evening of October 20, Musk declared that his two signature holdings have each named “special committees” composed of independent directors to explore a union. Musk’s statement confirmed Wall Street’s long-held view that the union was highly likely, and now—given that Musk effectively controls both companies and loves the idea (though as a “conflicted party” can’t serve on the committees), the tie-up looks all but inevitable.
The prospect of a SpaceX-Tesla combo got rave notices from the research crews covering both companies. In most cases where the acquirer is en route to paying a price amounting to a humongous PE, the acquirer’s stock falls. Not this time. This time, investors applauded both enterprises, sending Tesla up 3.4% the day following Musk’s statement and SpaceX up 7.8%, adding $155 billion in market cap.
At first glance, their already tight kinship, and all their many overlapping businesses, suggest that a new SpaceX-Tesla makes sense. SpaceX buys Tesla Megapack batteries and Cybertrucks, Tesla invested $2 billion in xAI, bought by SpaceX in February, and they share ownership of the much-feted chip project Terafab. Not to mention that the deal would clinch Musk’s long-harbored vision of running a single colossus as a kind of Berkshire Hathaway of AI-driven tech. The wizard freed to blend these two great elixirs of innovation? What’s not to like?
A close examination of claims made for the deal, especially assumptions on its supposed advantages in bolstering the finances of both companies, points to an extremely risky wager that must perform never-before-seen heroics to reward shareholders. It’s the ultimate, buy the leap of faith, it’s about the vision, not the numbers, never bet against Elon scenario, set against the sobering numbers. Let’s explore four frequently made arguments for what would prove the largest and, so far, probably the most universally praised, merger in the annals of capitalism.
SpaceX-Tesla would be accretive to SpaceX shareholders
The idea is that while SpaceX profits are just starting to accelerate, adding Tesla’s earnings, generated from its bedrock EV sales, would immediately raise the former’s EPS. In fact, it’s technically true: If the pair combined now, that’s how the math would work. The problem: The addition to SpaceX’s GAAP profits per share would be minuscule, and since SpaceX’s bottom line’s growing and Tesla’s dropping, the deal if done a year or two from now would prove extremely dilutive for the Starlink provider.
What stands out when you examine what SpaceX would pay versus what earnings it would get is how shockingly expensive the transaction would be.
One big question: How much premium would SpaceX offer over Tesla’s current price? As Rajat Gupta of JPMorgan points out in a report on a likely merger, that number in most tech acquisitions is 30% to 35%. So let’s posit 30%. Right now, Tesla’s market cap is $1.52 trillion; tack on 30%, and SpaceX would be out $1.98 trillion. SpaceX’s valuation stands at $2.14 trillion. We’re looking at almost a merger of equals. SpaceX would need to issue the equivalent of 92% of its current shares outstanding to capture Tesla. Hence, SpaceX’s count would zoom from 13.1 billion to 25 billion shares.
SpaceX would be awarding nearly half of its future earnings to Tesla’s selling shareholders, And what’s it getting in return? We don’t know what the robots and self-driving cars will deliver, but we do know that Tesla booked just $3.28 billion in GAAP net profits over the past four quarters. Since SpaceX had a $1.5 billion loss over the past four quarters, the deal would be “accretive” in the sense that buying Tesla would make the combined company slightly profitable. But SpaceX would just go from EPS that’s a minuscule negative to a tiny positive.
What’s important is the amount SpaceX is paying for those earnings and puny “accretion.” It would be getting $3.28 billion in profits in exchange for stock worth $1.98 trillion. That’s $600 for every $1 in extra earnings.
To make matters worse, Tesla’s profits have been falling while SpaceX’s bottom line is taking off. In Q3, SpaceX reversed the three prior quarters of deficits by registering $4.4 billion in GAAP net profits, enough to lower its 4-quarter loss to that $1.5 billion. In other words, profits are trending the right way, big time. Via a merger, SpaceX would be sacrificing half of those fast-rising earnings to the Tesla shareholders, and getting what’s for now a minimal contribution from Tesla. On the “accretion” argument, it looks like a bad outcome for SpaceX shareholders.
But overall, this would be a good deal for SpaceX, right?
Even if SpaceX didn’t buy Tesla, its valuation is so gigantic alongside its earnings that only by achieving stupendous growth in revenues and profits can it deliver shareholders an even decent return. In May, David Trainer of New Constructs provided math reckoning that at its current valuation of $2.14 trillion, SpaceX would need to be generating around $300 billion in profits on sales of roughly $1.6 trillion by 2035 to provide a competitive return. That’s a tall order, to put it mildly. The profits number would be almost a quarter more than what Alphabet makes now, on over three times its revenues. The rub: A Tesla acquisition simply gives SpaceX a far steeper hill to climb, one that’s almost twice as steep.
If SpaceX shoulders a 30% premium, the combined companies would start life with a market cap of $4.12 trillion. (That’s SpaceX’s current $2.14 trillion plus the $1.98 trillion paid for Tesla.) SpaceX 2.0 would edge Alphabet ($4.0 trillion) and Microsoft ($3.9 trillion) to rank as the third-most-valuable enterprise in America behind only Nvidia ($5.3 trillion). and Apple ($5.0 trillion). By Fortune’s estimate, SpaceX would need $550 billion in profits and around $3 trillion in revenue to ring the bell by 2035. That $550 billion target is over twice what Alphabet amasses today.
Once again, if Tesla were bringing already big and fast-rising profits to the table, the task wouldn’t be nearly as difficult. But it’s just the opposite. The EV-maker’s providing minimal profits that have already declined from $15 billion in 2023, and $5 billion in 2024 to a run rate that two-thirds the figure of just two years ago.
Tesla would help SpaceX with what it needs most, lots of cash flow to pay for its big, pricey AI adventure
Much of the attention on SpaceX’s financials focuses on its incredible cash burn that’s chiefly financing its ambitions in AI, or what it now calls “Super Intelligence.” In the first nine months of this year, SpaceX pocketed $13.1 billion in cash from operations, and lavished $48.1 billion in capex, of which $40 billion went to AI projects, chiefly the buildup in terrestrial data campuses and what it sees as tomorrow’s cash cow, AI centers in space, for negative free cash flow of $15 billion. What’s more, CFO Bret Johnson disclosed on the earnings call plans for $35 billion to $50 billon in investment just for Q4 alone.
SpaceX is seeking to raise an extra $40 billion in debt to help fund the campaign, but even fans on Wall Street question how SpaceX will raise the massive sums required. In its previous incarnation as an EV specialist, Tesla could have helped. Until this year, it typically provided large amounts of free cash flow. But now that Musk’s repurposed Tesla as a robotics and self-driving franchise, it’s in a similar position to SpaceX though on a lesser scale.
In its just-released results for Q3, Tesla registered negative free cash flow of $1.1 billion. And Musk says that he plans to spend a huge $25 billion in total capex this year, leaving at least $9 billion for Q4. That’s more than double the cash Tesla’s been garnering from operations in the last few quarters, meaning that will have a much bigger cash deficit in the final three months of 2026.
So putting SpaceX and Tesla together unites two companies that are super-hungry for cash. If you simply extrapolate the numbers, it’s likely that SpaceX and Tesla combined will spend close to a staggering $50 billion on capex in Q4, and their businesses won’t come close to covering that number. Looking forward, adding Tesla will simply make a new SpaceX’s huge need for cash far more acute.
A sale to SpaceX would be a great deal for Tesla shareholders, correct?
This one gets a ringing endorsement. Tesla’s shares now look vastly overvalued versus the basics. At its current market cap of $1.52 trillion, Tesla is selling at a PE of 633. Shareholders are getting one-sixth of a penny in earnings for every dollar they own in Tesla shares. And Tesla’s core, repeatable profits are actually lower than the reported numbers. They drop considerably when you back out sales of regulatory credits, a category Musk himself says will disappear, and unrealized gains on its SpaceX stake. So what explains this phenomenon where profits keep falling and the market cap remains in the stratosphere? As Steve Eisman explained to me in a recent story, it’s the prospect of a full-price buyout from SpaceX that’s supporting Tesla shares. Says Trainer, “A SpaceX deal is the only way to bail out Tesla shareholders.”
So if SpaceX indeed buys Tesla, it’s the Tesla owners who will prove the winners. And that’s the outcome they’re counting on. The losers will be SpaceX’s current shareholders that give up almost half their company for puny profits and big promises.
This story was originally featured on Fortune.com